Establish the baseline
Record discharge or processing time, material conditions and operator interventions using the current method.
A temporary Resonator installation under real operating conditions. Establish the baseline, apply the solution and measure whether the process improves before committing to a long-term model.
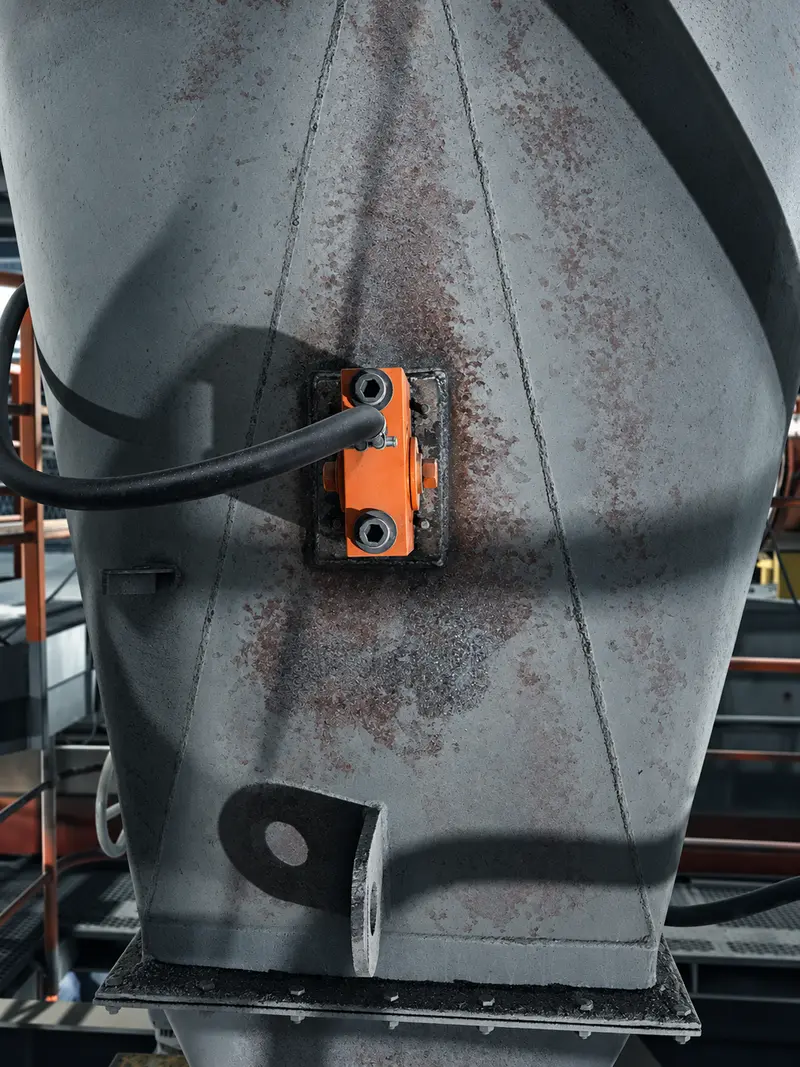
Agree the test scope, material quantity and acceptance criteria before arranging samples or an on-site demonstration.
Record discharge or processing time, material conditions and operator interventions using the current method.
Select the vibrator, mounting and pneumatic settings for the equipment and agreed task.
Repeat under comparable conditions. Measure cycle time, quality, air consumption and manual interventions.
Review a short report with recorded results, agreed video evidence and an estimate of operating value based on your production data.
The measurement plan is agreed before installation so both parties know what success means.
Production rate, discharge rate or units per cycle.
Frequency and duration of bridging, accumulation or stoppage.
Time required to reach the accepted process endpoint.
Density, homogeneity, voids, consistency or other product criteria.
Lost production and operator intervention before and after installation.
Pneumatic demand, maintenance events and current system costs where measurable.
Part or all of the pilot fee can be credited toward the final agreement when defined in the proposal.
The equipment is removed if the agreed result is not achieved or no long-term model is selected.
Convert the validated installation into a capital purchase.
Continue through a monthly Resonator as a Service contract.
Enter a Performance Partnership when economic value can be verified.
Tell us the material, machine, current method, recurring loss and measurable result you want to improve.
Enter your baseline and a measured or proposed trial scenario. No percentage improvement is assumed.
Enter all five values to calculate.
Planning estimate from your inputs, not a RESONATOR performance result. Use contribution after variable costs and avoid counting the same benefit twice.